Mazyad tower1, 7th Floor ,Office # 37 , PO Box: 6001 , Abu-Dhabi - U.A.E.
Navigating the complexities of modern financial planning can feel overwhelming. Individuals and families alike are constantly seeking ways to secure their financial future, optimize investments, and achieve their long-term goals. Fortunately, a wealth of resources are available to empower informed decision-making. One such resource is https://bonrush-uk.co.uk, a platform designed to offer support and guidance in various aspects of personal finance. Understanding your options, from budgeting and saving to investing and retirement planning, is crucial in today's economic climate.
Effective financial planning isn't a one-size-fits-all solution; it requires a personalized approach tailored to individual circumstances, risk tolerance, and financial objectives. It involves a continuous process of assessment, planning, implementation, and review. Many people underestimate the power of early financial planning, believing it’s something only relevant later in life. However, starting early, even with small steps, can yield substantial benefits over time. Building a solid financial foundation is an investment in peace of mind and future security, allowing you to pursue your aspirations with confidence.
Before diving into specific investment strategies or retirement plans, it's essential to gain a comprehensive understanding of your current financial situation. This involves meticulously tracking your income, expenses, assets, and liabilities. A clear picture of your cash flow – the money coming in and going out – is the cornerstone of effective financial management. Many people find creating a detailed budget to be a surprisingly empowering exercise. It highlights areas where you can potentially save money and redirect those funds towards achieving your financial goals. It’s also important to assess your debt levels, categorizing them by interest rate and repayment terms. Prioritizing high-interest debt, such as credit card balances, can save you a significant amount of money over the long run. Regularly reviewing your credit report is crucial for identifying and correcting any errors that could negatively impact your credit score.
Establishing clear and achievable financial goals provides the motivation and direction needed to stay on track. These goals should be specific, measurable, attainable, relevant, and time-bound – often referred to as SMART goals. For example, instead of simply stating “I want to save for retirement,” a SMART goal would be “I want to contribute 15% of my income to my retirement account each month for the next 30 years.” Goals can range from short-term objectives, such as building an emergency fund, to long-term aspirations, like purchasing a home or funding your children’s education. Breaking down larger goals into smaller, more manageable steps can make the process less daunting and more attainable. Regularly revisiting and adjusting your goals as your life circumstances change is also essential for maintaining relevance and motivation.
| Financial Goal | Time Horizon | Estimated Cost | Monthly Savings Required |
|---|---|---|---|
| Emergency Fund | Short-Term (6-12 months) | £3,000 – £6,000 | £250 – £500 |
| Down Payment on a Home | Medium-Term (5-10 years) | £20,000 – £50,000 | £333 – £833 |
| Retirement | Long-Term (20+ years) | Varies significantly | 10-15% of Income |
| Children's Education | Medium to Long-Term | £40,000+ per child | £200+ per month |
This table illustrates the rough estimates for different financial goals. It’s important to remember that these are just examples and individual circumstances will vary significantly. Using tools available online or consulting with a financial advisor can help you create a more personalized savings plan.
Once you have a solid understanding of your financial situation and have established clear goals, you can begin exploring investment strategies to grow your wealth. There are numerous investment options available, each with its own level of risk and potential return. Stocks, bonds, mutual funds, and exchange-traded funds (ETFs) are some of the most common investment vehicles. Diversification – spreading your investments across different asset classes – is a key principle of risk management. It helps to mitigate potential losses by ensuring that your portfolio isn't overly reliant on any single investment. The level of risk you're comfortable with should heavily influence your investment choices. Younger investors with a longer time horizon may be able to tolerate more risk, while those closer to retirement may prefer more conservative investments.
Your risk tolerance is your ability and willingness to lose some of your investment in exchange for the potential for higher returns. It’s influenced by factors such as your age, income, financial goals, and personal temperament. There are several online risk assessment tools available that can help you determine your risk profile. It’s crucial to be honest with yourself when completing these assessments, as an inaccurate assessment could lead to investment choices that are not suitable for your needs. Remember that higher potential returns typically come with higher risk. It’s important to strike a balance between risk and reward that aligns with your individual circumstances and comfort level. Regularly reviewing your risk tolerance and adjusting your investment strategy as needed is also essential.
This overview provides a basic understanding of common investment options. Further research and, potentially, advice from a financial professional are recommended before making any investment decisions.
Planning for retirement is a critical component of long-term financial security. The earlier you start saving, the more time your investments have to grow through the power of compounding. Compounding is the process of earning returns on your initial investment and on the accumulated earnings. Over time, this can lead to substantial wealth accumulation. There are various retirement savings plans available, such as 401(k)s, IRAs, and pensions. Understanding the tax implications of each plan is crucial for maximizing your savings. For example, contributions to traditional IRAs may be tax-deductible, while distributions in retirement will be taxed. Roth IRAs, on the other hand, offer tax-free withdrawals in retirement but contributions are made with after-tax dollars. Estimating your retirement expenses is another important step. Consider factors such as healthcare costs, housing expenses, and lifestyle preferences.
Several strategies can help you maximize your retirement savings. First, take full advantage of any employer-sponsored retirement plans, such as 401(k)s, and contribute enough to receive the full employer match. This is essentially free money. Second, consider automating your savings by setting up regular contributions to your retirement accounts. This ensures that you consistently save, even when you’re busy or facing other financial obligations. Third, revisit your investment allocation periodically to ensure it still aligns with your risk tolerance and time horizon. Finally, consider consulting with a financial advisor to develop a personalized retirement plan that addresses your specific needs and goals. Resources like those found on platforms such as https://bonrush-uk.co.uk can offer valuable insights and tools to help you plan for a comfortable retirement.
Implementing these strategies can significantly enhance your retirement preparedness and help you achieve financial independence.
Insurance plays a vital role in protecting your financial well-being by mitigating the financial impact of unexpected events. Different types of insurance provide coverage for various risks, such as illness, injury, property damage, and premature death. Health insurance is essential for covering medical expenses, while life insurance provides financial support to your beneficiaries in the event of your death. Disability insurance protects your income if you become unable to work due to illness or injury. Property insurance, such as homeowners or renters insurance, covers damage or loss to your property. Carefully assessing your insurance needs and obtaining adequate coverage is crucial for safeguarding your financial future. It’s also important to regularly review your insurance policies to ensure they still meet your evolving needs.
Choosing the right insurance policies involves considering factors such as coverage limits, deductibles, and premiums. A higher deductible typically results in a lower premium, but it also means you’ll have to pay more out-of-pocket before your insurance coverage kicks in. It’s important to strike a balance between affordability and adequate coverage. Comparing quotes from different insurance providers can help you find the best value for your money.
Once you've established a solid foundation in basic financial planning, you can explore more advanced strategies to optimize your wealth and achieve your long-term goals. Estate planning, tax optimization, and charitable giving are examples of advanced financial techniques. Estate planning involves creating a plan for managing and distributing your assets after your death. Tax optimization strategies aim to minimize your tax liability through careful planning and utilization of tax-advantaged accounts. Charitable giving can not only provide financial support to worthy causes but also offer tax benefits. These strategies often require the expertise of qualified professionals, such as estate planning attorneys, tax advisors, and financial planners. The platform mentioned earlier, https://bonrush-uk.co.uk, can be a useful starting point for researching these topics and connecting with qualified advisors. Understanding your options and seeking professional guidance can help you navigate the complexities of these advanced financial strategies and maximize their potential benefits.
A fascinating example of leveraging advanced financial strategies involves utilizing trusts for estate planning. Trusts can protect assets from creditors, minimize estate taxes, and ensure that your assets are distributed according to your wishes. However, creating and maintaining a trust can be complex and requires the expertise of an experienced estate planning attorney. Similarly, tax-loss harvesting, a strategy that involves selling losing investments to offset capital gains, can help minimize your tax bill, but it requires careful planning and record-keeping.
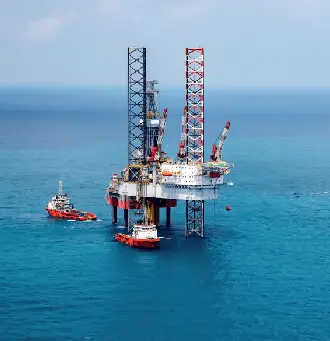
FOHMICS offer engineering and prime contracting services in fields related to the production and distribution of different types of energy. Our procurement teams work closely with engineers, clients and vendors to define requirements and ensure specifications and schedules are met.
FOHMICS offer engineering and prime contracting services in fields related to the production and distribution of different types of energy. Our procurement teams work closely with engineers, clients and vendors to define requirements and ensure specifications and schedules are met.
2026©All Rights Reserved FOHMICS OIL AND GAS EQUIPMENTS TRADING AND SERVICES - L.L.C . Developed by

